How much should be in your emergency fund?
A clear way to pick your number, and a realistic way to get there without feeling overwhelmed.
An emergency fund is money set aside for true surprises: a job loss, a car repair, a medical bill. Its job is to keep one bad week from turning into months of credit card debt.
The common rule: 3 to 6 months of essential expenses
Most guidance suggests saving three to six months of essential expenses. Notice it's expenses, not income, and only the essentials: housing, utilities, groceries, insurance, transportation and minimum debt payments.
If your essentials are $3,200 a month:
- 3 months: $9,600
- 6 months: $19,200
Our free emergency fund calculator works this out and shows how long it will take at your savings rate.
Should you aim for 3 months or 6?
Lean toward more if your income is irregular, you're self-employed, you're the only earner in your household, or your job would be hard to replace quickly. Three months can be enough if you have steady income, a second earner, or other savings you could tap.
Start with a starter fund
Six months of expenses can feel impossible. Don't start there. Start with a $1,000 starter fund, which covers many common surprises like a tire or a copay. Then build toward one month, then three.
Where to keep it
Keep your emergency fund somewhere safe, separate and easy to reach. A high-yield savings account at an FDIC-insured bank is a popular choice: your money earns some interest, it's not mixed with everyday spending, and you can usually move it in a day or two. It's generally not a good idea to keep emergency money in investments that can drop in value right when you need them.
How to build it faster
- Automate it. Set a transfer for the day after payday, even $25.
- Use windfalls. Tax refunds, bonuses and three-paycheck months can jump-start the fund.
- Name it. An account called "Emergency fund" is harder to raid for a sale.
When to use it (and when not to)
Use it for things that are necessary, urgent and unexpected. A holiday or a planned car registration isn't an emergency; those belong in a sinking fund. After you use it, make refilling it your next goal.
Thinking about a big purchase?
Six quick taps give you a clear verdict, the price in hours of work, and a save-up plan.
Check a purchase →Try the numbers yourself
Our free emergency fund calculator works it out in seconds. No sign-up.
Open the calculator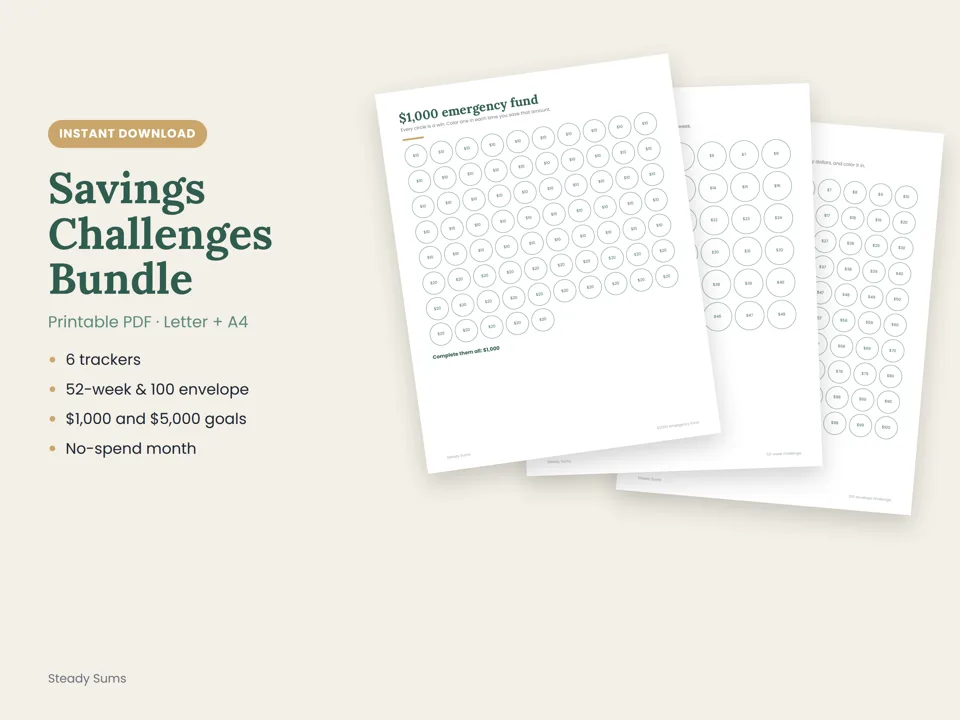
Make saving a game.
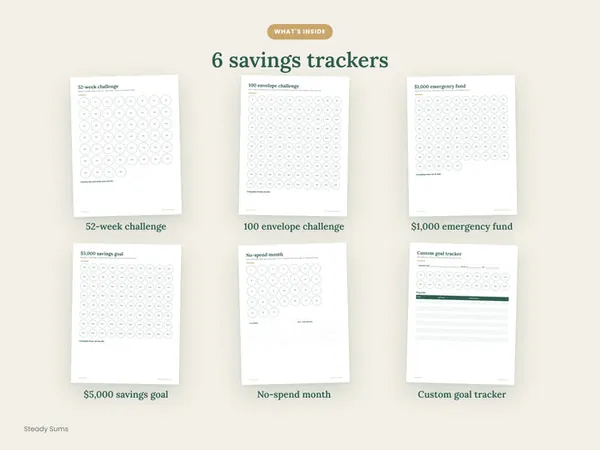
Printable savings challenges, from 52-week to $5,000 trackers. Color in a box every time you save.
Build your emergency fund one month at a time.
Budget, debt payoff and savings goals in one calm app, on your phone or computer. Free for 14 days, then $5/month. No card needed to start.
Try the Planner freeQuestions people ask
How much should a beginner have in an emergency fund?
A common first goal is $1,000. After that, build toward three to six months of essential expenses.
Should I pay off debt or build an emergency fund first?
Many people build a small starter fund first so surprises don't go on a credit card, then focus on high-interest debt while slowly growing savings.
Where should I keep my emergency fund?
Somewhere safe, separate from your checking account and easy to access, such as a high-yield savings account at an FDIC-insured bank.
Save this guide for later.
Pin it to your budgeting board so it's there when you need it.
Steady Sums shares general education, not financial advice. For decisions about your situation, talk to a licensed professional.
More money guides
Sinking funds: the easy way to pay for big expenses
Most budget-busting bills aren't emergencies. They're predictable expenses that show up once or twice a year.
Read the guide →The 52-week savings challenge: how to save $1,378 in a year
Save $1 in week one, $2 in week two, and so on. It starts easy, builds a habit, and ends with $1,378 saved.
Read the guide →How to do a no-spend challenge (and actually save money)
Pause everything except the essentials for a set time. It's a quick reset that shows you exactly where your money usually leaks.
Read the guide →Make it easier with the right tool
One calm money move a week.
A 3-minute Tuesday email with one simple step for budgeting, saving and paying off debt. Join free and get a printable $1,000 emergency fund tracker.
Free. One email a week. Unsubscribe any time.